

Update README.md
#1
by kashif HF Staff - opened
README.md
CHANGED
|
@@ -2,40 +2,21 @@
|
|
| 2 |
license: apache-2.0
|
| 3 |
pipeline_tag: time-series-forecasting
|
| 4 |
library_name: tfc-t0
|
| 5 |
-
thumbnail: https://www.theforecastingcompany.com/
|
| 6 |
tags:
|
| 7 |
- time-series
|
| 8 |
- forecasting
|
| 9 |
- probabilistic-forecasting
|
| 10 |
- foundation-models
|
| 11 |
- pretrained-models
|
| 12 |
-
- transformer
|
| 13 |
-
- multivariate
|
| 14 |
-
- known-future-covariates
|
| 15 |
-
- open-weights
|
| 16 |
- covariates
|
| 17 |
- pytorch
|
| 18 |
-
- mlx
|
| 19 |
-
- apple-silicon
|
| 20 |
- safetensors
|
| 21 |
- model_hub_mixin
|
| 22 |
- pytorch_model_hub_mixin
|
| 23 |
model-index:
|
| 24 |
- name: t0-alpha
|
| 25 |
results:
|
| 26 |
-
- task:
|
| 27 |
-
type: time-series-forecasting
|
| 28 |
-
name: Time Series Forecasting
|
| 29 |
-
dataset:
|
| 30 |
-
name: fev-bench
|
| 31 |
-
type: autogluon/fev-bench
|
| 32 |
-
metrics:
|
| 33 |
-
- name: Skill score
|
| 34 |
-
type: skill-score
|
| 35 |
-
value: 42.2
|
| 36 |
-
source:
|
| 37 |
-
name: fev-bench leaderboard
|
| 38 |
-
url: https://huggingface.co/spaces/autogluon/fev-bench
|
| 39 |
- task:
|
| 40 |
type: time-series-forecasting
|
| 41 |
name: Time Series Forecasting
|
|
@@ -55,25 +36,18 @@ model-index:
|
|
| 55 |
---
|
| 56 |
|
| 57 |
<p align="center">
|
| 58 |
-
<img
|
| 59 |
-
<img class="hidden dark:block" src="https://www.theforecastingcompany.com/logo/logo_horizontal_dark.png" alt="The Forecasting Company" width="280" />
|
| 60 |
</p>
|
| 61 |
|
| 62 |
# `t0-alpha`
|
| 63 |
|
| 64 |
-
<p align="center">
|
| 65 |
-
<a href="https://arxiv.org/abs/2609.24559"><img src="https://img.shields.io/badge/arXiv-2609.24559-b31b1b.svg" alt="arXiv" /></a>
|
| 66 |
-
</p>
|
| 67 |
-
|
| 68 |
`t0-alpha` is an open-weights time-series forecasting foundation model from [The Forecasting Company](https://theforecastingcompany.com/).
|
| 69 |
|
| 70 |
`t0` is a transformer-based model that produces probabilistic multi-horizon forecasts and natively operates on multiple covariates. `t0-alpha` is the first public iteration of the model.
|
| 71 |
|
| 72 |
You can use `t0` on [Retrocast](https://app.retrocast.com/), The Forecasting Company's platform for forecasting on your own data and comparing forecasts across open-weight models.
|
| 73 |
|
| 74 |
-
|
| 75 |
-
|
| 76 |
-
|
| 77 |
|
| 78 |
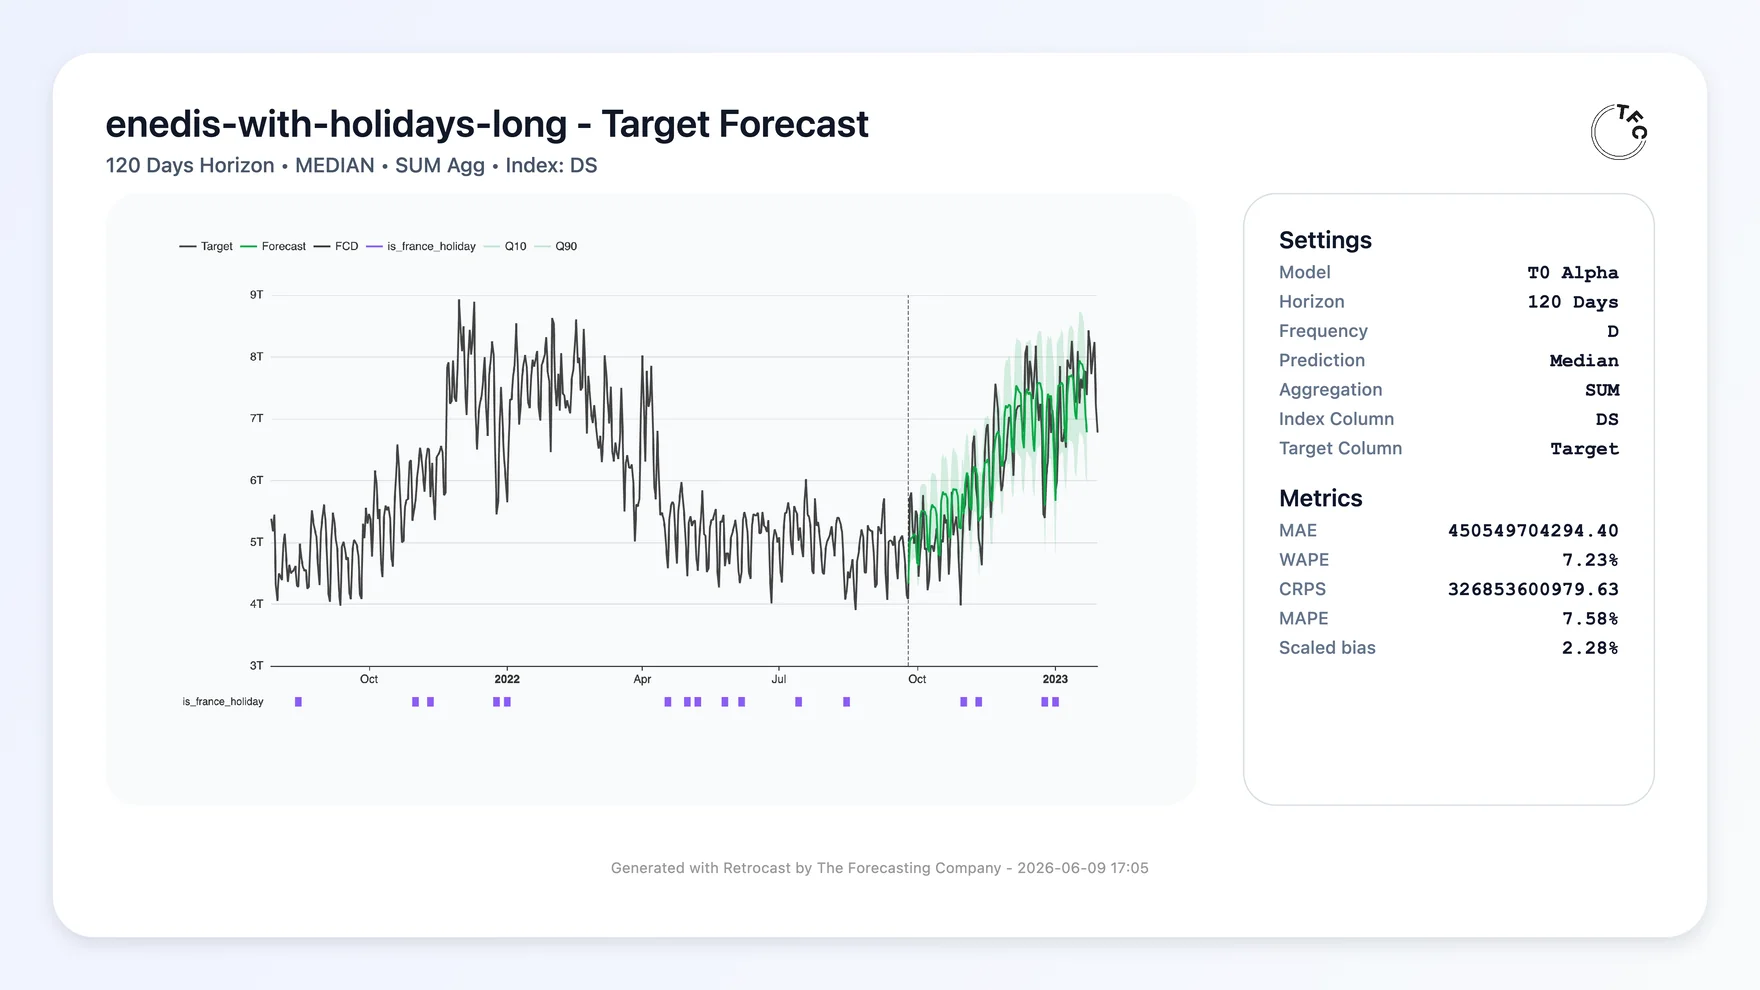
_`t0` forecasting French national electricity demand in Retrocast. Data: [Enedis open data](https://data.enedis.fr/)._
|
| 79 |
|
|
@@ -87,9 +61,9 @@ _`t0` forecasting French national electricity demand in Retrocast. Data: [Enedis
|
|
| 87 |
- Parameters: approximately 102M
|
| 88 |
- License: Apache-2.0
|
| 89 |
- Weights: https://huggingface.co/theforecastingcompany/t0-alpha
|
| 90 |
-
-
|
| 91 |
-
-
|
| 92 |
-
-
|
| 93 |
|
| 94 |
`t0-alpha` is an alpha release intended for research, experimentation, and applied forecasting evaluation.
|
| 95 |
|
|
@@ -107,7 +81,7 @@ Forecasts should be treated as probabilistic estimates, not guarantees.
|
|
| 107 |
|
| 108 |
| Without covariates | With covariates |
|
| 109 |
| ----------------------------------------------------------------- | ----------------------------------------------------------- |
|
| 110 |
-
| , monthly drug reimbursements from the French national health insurance._
|
| 113 |
|
|
@@ -115,40 +89,20 @@ The [Quickstart](#quickstart) below shows the API for both a plain univariate fo
|
|
| 115 |
|
| 116 |
## Installation
|
| 117 |
|
| 118 |
-
Choose a runtime for the same original `t0-alpha` checkpoint. Both local runtimes
|
| 119 |
-
ship in the `tfc-t0` package, each behind an extra; a bare `pip install tfc-t0`
|
| 120 |
-
installs neither runtime: choose one with its extra.
|
| 121 |
-
|
| 122 |
-
| Runtime | Best for | Install |
|
| 123 |
-
| --- | --- | --- |
|
| 124 |
-
| PyTorch | Broad hardware support and the PyTorch ecosystem | `pip install "tfc-t0[torch]"` |
|
| 125 |
-
| MLX | Local, inference-only use on Apple silicon | `pip install "tfc-t0[mlx]>=0.6.0"` |
|
| 126 |
-
| ONNX FP16 | Accelerator-oriented local and edge deployments | [`t0-alpha-onnx-fp16`](https://huggingface.co/theforecastingcompany/t0-alpha-onnx-fp16) |
|
| 127 |
-
| ONNX INT8 | CPU and in-browser inference | [`t0-alpha-onnx-int8`](https://huggingface.co/theforecastingcompany/t0-alpha-onnx-int8) |
|
| 128 |
-
| Managed API | Hosted inference without local weights | [`theforecastingcompany` SDK](https://pypi.org/project/theforecastingcompany/) |
|
| 129 |
-
|
| 130 |
-
### PyTorch
|
| 131 |
-
|
| 132 |
```bash
|
| 133 |
-
pip install
|
| 134 |
```
|
| 135 |
|
| 136 |
Requirements:
|
| 137 |
|
| 138 |
-
- Python `>=3.
|
| 139 |
-
- PyTorch `>=2.4`
|
| 140 |
|
| 141 |
Optional extras:
|
| 142 |
|
| 143 |
```bash
|
| 144 |
-
pip install "tfc-t0[evaluation]"
|
| 145 |
-
pip install "tfc-t0[
|
| 146 |
-
```
|
| 147 |
-
|
| 148 |
-
### MLX on Apple silicon
|
| 149 |
-
|
| 150 |
-
```bash
|
| 151 |
-
pip install "tfc-t0[mlx]>=0.6.0"
|
| 152 |
```
|
| 153 |
|
| 154 |
## 🚀 Quickstart
|
|
@@ -162,36 +116,16 @@ from t0 import T0Forecaster
|
|
| 162 |
model = T0Forecaster.from_pretrained("theforecastingcompany/t0-alpha").eval()
|
| 163 |
|
| 164 |
context = torch.randn(4, 512) # 4 series, 512 past timesteps
|
| 165 |
-
out = model.predict(context, horizon=64,
|
| 166 |
out.quantiles # (4, 64, 3)
|
| 167 |
out.median # (4, 64)
|
| 168 |
```
|
| 169 |
|
| 170 |
`predict` accepts PyTorch tensors and NumPy arrays.
|
| 171 |
|
| 172 |
-
### MLX Quickstart
|
| 173 |
-
|
| 174 |
-
The MLX runtime deliberately follows the same forecasting interface:
|
| 175 |
-
|
| 176 |
-
```python
|
| 177 |
-
import numpy as np
|
| 178 |
-
from t0.mlx import T0Forecaster
|
| 179 |
-
|
| 180 |
-
model = T0Forecaster.from_pretrained("theforecastingcompany/t0-alpha").eval()
|
| 181 |
-
context = np.random.randn(4, 512).astype(np.float32)
|
| 182 |
-
|
| 183 |
-
out = model.predict(context, horizon=64, quantile_levels=[0.1, 0.5, 0.9])
|
| 184 |
-
out.quantiles.shape # (4, 64, 3)
|
| 185 |
-
out.median.shape # (4, 64)
|
| 186 |
-
```
|
| 187 |
-
|
| 188 |
-
See [the MLX runtime](https://github.com/theforecastingcompany/tfc-t0#mlx-runtime-apple-silicon) for
|
| 189 |
-
feature coverage, compilation guidance and reproducible Apple-silicon
|
| 190 |
-
benchmarks.
|
| 191 |
-
|
| 192 |
### Forecasting With Covariates
|
| 193 |
|
| 194 |
-
Anything known over the past goes in `context`. Alongside the target, extra variates attend to it and are forecast together. Anything known over the future, such as calendar features, planned promotions, or weather forecasts, goes in `future_covariates`, shaped `[B, F, context + horizon]`
|
| 195 |
|
| 196 |
```python
|
| 197 |
import torch
|
|
@@ -205,98 +139,24 @@ future_covariates = torch.randn(2, 3, 512 + 64) # 3 covariates known over conte
|
|
| 205 |
out = model.predict(
|
| 206 |
context,
|
| 207 |
horizon=64,
|
| 208 |
-
|
| 209 |
future_covariates=future_covariates,
|
| 210 |
)
|
| 211 |
out.quantiles # (2, 64, 3)
|
| 212 |
out.median # (2, 64)
|
| 213 |
```
|
| 214 |
|
| 215 |
-
### Batched Inference
|
| 216 |
-
|
| 217 |
-
```python
|
| 218 |
-
import numpy as np
|
| 219 |
-
from t0 import T0Forecaster, batch_series
|
| 220 |
-
|
| 221 |
-
model = T0Forecaster.from_pretrained("theforecastingcompany/t0-alpha").eval()
|
| 222 |
-
|
| 223 |
-
daily = np.random.randn(180) # one series, 180 past timesteps
|
| 224 |
-
store = np.random.randn(2, 96) # one series of 2 variates, 96 past timesteps
|
| 225 |
-
hourly = np.random.randn(1024) # one series, 1024 past timesteps
|
| 226 |
-
|
| 227 |
-
context, mask, group_ids = batch_series([daily, store, hourly])
|
| 228 |
-
context.shape # (4, 1024) — variates stacked, right-aligned to the longest series
|
| 229 |
-
group_ids # [0, 1, 1, 2] — `store`'s two variates are forecast jointly
|
| 230 |
-
|
| 231 |
-
out = model.predict(context, horizon=24, quantile_levels=[0.1, 0.5, 0.9], mask=mask, group_ids=group_ids)
|
| 232 |
-
out.quantiles # (4, 24, 3)
|
| 233 |
-
out.median[0] # the 24-step median forecast for `daily`
|
| 234 |
-
```
|
| 235 |
-
|
| 236 |
-
Integrations that prepare complete T0 inputs, including known-future
|
| 237 |
-
covariates, can batch the native representation directly:
|
| 238 |
-
|
| 239 |
-
```python
|
| 240 |
-
from t0 import TimeSeries
|
| 241 |
-
|
| 242 |
-
first = TimeSeries.from_array(context_1, future_covariates_1)
|
| 243 |
-
second = TimeSeries.from_array(context_2, future_covariates_2)
|
| 244 |
-
batch = TimeSeries.batch([first, second])
|
| 245 |
-
|
| 246 |
-
out = model.predict(
|
| 247 |
-
batch,
|
| 248 |
-
horizon=64,
|
| 249 |
-
context_length=max(context_1.shape[-1], context_2.shape[-1]),
|
| 250 |
-
)
|
| 251 |
-
```
|
| 252 |
-
|
| 253 |
-
Here each context includes its batch axis, for example `[1, V, T]`, and each
|
| 254 |
-
known-future input is `[1, F, T + horizon]`. The output is ordered by the
|
| 255 |
-
flattened target rows in `batch`.
|
| 256 |
-
|
| 257 |
-
### Converting your data to `TimeSeries`
|
| 258 |
-
|
| 259 |
-
`TimeSeries` is the model's native input. It holds target rows, known-future
|
| 260 |
-
covariate rows, a mask and group ids, all on one width. `predict` builds one for
|
| 261 |
-
you from a raw array. You only need to construct one yourself to batch inputs of
|
| 262 |
-
different widths, or to call `forward` directly.
|
| 263 |
-
|
| 264 |
-
```python
|
| 265 |
-
from t0 import TimeSeries
|
| 266 |
-
|
| 267 |
-
# context only, with `horizon` marking the region to predict
|
| 268 |
-
model_input = TimeSeries.from_array(context, horizon=24) # context: [B, V, T]
|
| 269 |
-
|
| 270 |
-
# with known-future covariates, whose width sets the horizon
|
| 271 |
-
model_input = TimeSeries.from_array(context, future_covariates) # covariates: [B, F, T + 24]
|
| 272 |
-
|
| 273 |
-
out = model.predict(model_input, horizon=24, quantile_levels=[0.1, 0.5, 0.9])
|
| 274 |
-
```
|
| 275 |
-
|
| 276 |
-
`predict` infers `context_length` from where the forecast region starts. Pass it
|
| 277 |
-
explicitly when batching series of different widths. `forward` takes the same
|
| 278 |
-
`TimeSeries` and runs a single differentiable pass over it, with no rollout. That
|
| 279 |
-
is the entry point for fine-tuning.
|
| 280 |
-
|
| 281 |
-
**For efficient inference at scale, look at [Retrocast](https://app.retrocast.com/).**
|
| 282 |
-
|
| 283 |
## Input Contract
|
| 284 |
|
| 285 |
- `context` may be shaped `(B, T)` for batched univariate forecasting.
|
| 286 |
-
- `context` may also be shaped `(T,)`
|
| 287 |
- `context` may be shaped `(B, V, T)` for multiple target variates.
|
| 288 |
- `future_covariates`, when provided, should be shaped `(B, F, context + horizon)`.
|
| 289 |
-
-
|
| 290 |
-
- NaN in `context` is read as an absent observation. Padding is the case NaN cannot express, so a batch of unequal-length series needs a `mask` (or `batch_series`) to declare it.
|
| 291 |
-
- Patches made entirely of `PAD` stay out of attention.
|
| 292 |
-
- `group_ids`, when provided, holds one id per row of the context. Rows sharing an id are variates of one series and are forecast jointly.
|
| 293 |
-
- `group_ids` cannot be combined with `future_covariates`, which are addressed per sample.
|
| 294 |
-
- NaN in `future_covariates` is treated as missing.
|
| 295 |
- `horizon` must be at least 1.
|
| 296 |
- Requested quantiles must be non-empty, sorted ascending, unique, and in `(0, 1)`.
|
| 297 |
- The model was trained to emit quantiles `0.1`, `0.25`, `0.5`, `0.75`, and `0.9`.
|
| 298 |
-
- Requested
|
| 299 |
-
them follow exponential tails pinned through the outermost trained levels.
|
| 300 |
- Horizons up to 1024 timesteps are decoded in one forward pass.
|
| 301 |
- Longer horizons use autoregressive rollout.
|
| 302 |
- Returned forecasts are finite `float32` tensors on the model's device.
|
|
@@ -305,7 +165,9 @@ is the entry point for fine-tuning.
|
|
| 305 |
|
| 306 |
`t0` is a decoder-style patch transformer.
|
| 307 |
|
| 308 |
-
It encodes each patch from values, within-patch time index, and validity mask. The transformer alternates causal time-axis self-attention with variate-axis group self-attention.
|
|
|
|
|
|
|
| 309 |
|
| 310 |
| Field | Value |
|
| 311 |
| --- | --- |
|
|
@@ -318,33 +180,25 @@ It encodes each patch from values, within-patch time index, and validity mask. T
|
|
| 318 |
| Feedforward dim | 2048 |
|
| 319 |
| Attention heads | 8 |
|
| 320 |
| Patch size | 32 |
|
|
|
|
| 321 |
| Scaler | causal mean/std with `arcsinh` transform |
|
| 322 |
| Native quantile levels | 0.1, 0.25, 0.5, 0.75, 0.9 |
|
| 323 |
|
| 324 |
## Evaluation
|
| 325 |
|
| 326 |
-
`t0-alpha` is reported on the [GIFT-Eval leaderboard](https://huggingface.co/spaces/Salesforce/GIFT-Eval)
|
| 327 |
|
| 328 |
-
| Benchmark |
|
| 329 |
-
| --- | --- | ---: |
|
| 330 |
-
| GIFT-Eval |
|
| 331 |
-
| GIFT-Eval | MASE | 0.7240 |
|
| 332 |
-
| fev-bench | Skill score | 42.2 |
|
| 333 |
|
| 334 |
Users should also evaluate `t0-alpha` on their own historical backtests. Useful checks include quantile loss, CRPS, MASE, empirical quantile coverage, calibration, and breakdowns by frequency, horizon, domain, history length, and covariate availability.
|
| 335 |
|
| 336 |
## 🧰 Public API
|
| 337 |
|
| 338 |
-
- `T0Forecaster`:
|
| 339 |
-
- `Forecast`:
|
| 340 |
-
- `T0Config`:
|
| 341 |
-
- `MaskType`: the reason a time step is masked out.
|
| 342 |
-
- `VariateType`: whether a row is a target, a historical covariate or a
|
| 343 |
-
known-future covariate.
|
| 344 |
-
- `batch_series`: utility to batch time series of potentially different lengths.
|
| 345 |
-
- `TimeSeries.from_array` / `TimeSeries.batch`: build the model's native input,
|
| 346 |
-
including known-future covariates and an explicit forecast `horizon`.
|
| 347 |
-
`predict` accepts either a `TimeSeries` or a raw context array.
|
| 348 |
|
| 349 |
## 🧬 Lineage and Attributions
|
| 350 |
|
|
@@ -353,26 +207,29 @@ Users should also evaluate `t0-alpha` on their own historical backtests. Useful
|
|
| 353 |
- **Toto** by Datadog ([repo](https://github.com/DataDog/toto)) and **Chronos-2** by Amazon ([repo](https://github.com/amazon-science/chronos-forecasting)) for factorizing attention in the time and variates dimension.
|
| 354 |
- **TiRex** by NXAI ([repo](https://github.com/NX-AI/tirex)) for contiguous patch masking.
|
| 355 |
|
| 356 |
-
Code-level attributions are listed in [`NOTICE`](
|
| 357 |
|
| 358 |
-
##
|
| 359 |
|
| 360 |
-
|
|
|
|
|
|
|
| 361 |
|
| 362 |
```bibtex
|
| 363 |
-
@
|
| 364 |
-
title
|
| 365 |
-
author
|
| 366 |
-
|
| 367 |
-
|
| 368 |
-
url = {https://arxiv.org/abs/2609.24559},
|
| 369 |
}
|
| 370 |
```
|
| 371 |
|
| 372 |
## ⚖️ License
|
| 373 |
|
| 374 |
-
Apache-2.0. See [`LICENSE`](
|
| 375 |
|
| 376 |
## Contact
|
| 377 |
|
| 378 |
-
For issues
|
|
|
|
|
|
|
|
|
| 2 |
license: apache-2.0
|
| 3 |
pipeline_tag: time-series-forecasting
|
| 4 |
library_name: tfc-t0
|
| 5 |
+
thumbnail: https://www.theforecastingcompany.com/images/og.png
|
| 6 |
tags:
|
| 7 |
- time-series
|
| 8 |
- forecasting
|
| 9 |
- probabilistic-forecasting
|
| 10 |
- foundation-models
|
| 11 |
- pretrained-models
|
|
|
|
|
|
|
|
|
|
|
|
|
| 12 |
- covariates
|
| 13 |
- pytorch
|
|
|
|
|
|
|
| 14 |
- safetensors
|
| 15 |
- model_hub_mixin
|
| 16 |
- pytorch_model_hub_mixin
|
| 17 |
model-index:
|
| 18 |
- name: t0-alpha
|
| 19 |
results:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 20 |
- task:
|
| 21 |
type: time-series-forecasting
|
| 22 |
name: Time Series Forecasting
|
|
|
|
| 36 |
---
|
| 37 |
|
| 38 |
<p align="center">
|
| 39 |
+
<img src="https://www.theforecastingcompany.com/logo/logo_horizontal_pride_universal.png" alt="The Forecasting Company" width="280" />
|
|
|
|
| 40 |
</p>
|
| 41 |
|
| 42 |
# `t0-alpha`
|
| 43 |
|
|
|
|
|
|
|
|
|
|
|
|
|
| 44 |
`t0-alpha` is an open-weights time-series forecasting foundation model from [The Forecasting Company](https://theforecastingcompany.com/).
|
| 45 |
|
| 46 |
`t0` is a transformer-based model that produces probabilistic multi-horizon forecasts and natively operates on multiple covariates. `t0-alpha` is the first public iteration of the model.
|
| 47 |
|
| 48 |
You can use `t0` on [Retrocast](https://app.retrocast.com/), The Forecasting Company's platform for forecasting on your own data and comparing forecasts across open-weight models.
|
| 49 |
|
| 50 |
+

|
|
|
|
|
|
|
| 51 |
|
| 52 |
_`t0` forecasting French national electricity demand in Retrocast. Data: [Enedis open data](https://data.enedis.fr/)._
|
| 53 |
|
|
|
|
| 61 |
- Parameters: approximately 102M
|
| 62 |
- License: Apache-2.0
|
| 63 |
- Weights: https://huggingface.co/theforecastingcompany/t0-alpha
|
| 64 |
+
- Source code: https://github.com/theforecastingcompany/tfc-t0
|
| 65 |
+
- Issues: https://github.com/theforecastingcompany/tfc-t0/issues
|
| 66 |
+
- Package: `tfc-t0`
|
| 67 |
|
| 68 |
`t0-alpha` is an alpha release intended for research, experimentation, and applied forecasting evaluation.
|
| 69 |
|
|
|
|
| 81 |
|
| 82 |
| Without covariates | With covariates |
|
| 83 |
| ----------------------------------------------------------------- | ----------------------------------------------------------- |
|
| 84 |
+
|  |  |
|
| 85 |
|
| 86 |
_Data: [Medic'AM](https://www.assurance-maladie.ameli.fr/etudes-et-donnees/medicaments-classe-atc-medicam), monthly drug reimbursements from the French national health insurance._
|
| 87 |
|
|
|
|
| 89 |
|
| 90 |
## Installation
|
| 91 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 92 |
```bash
|
| 93 |
+
pip install tfc-t0
|
| 94 |
```
|
| 95 |
|
| 96 |
Requirements:
|
| 97 |
|
| 98 |
+
- Python `>=3.11,<3.14`
|
| 99 |
+
- PyTorch `>=2.4,<3`
|
| 100 |
|
| 101 |
Optional extras:
|
| 102 |
|
| 103 |
```bash
|
| 104 |
+
pip install "tfc-t0[evaluation]"
|
| 105 |
+
pip install "tfc-t0[plot]"
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 106 |
```
|
| 107 |
|
| 108 |
## 🚀 Quickstart
|
|
|
|
| 116 |
model = T0Forecaster.from_pretrained("theforecastingcompany/t0-alpha").eval()
|
| 117 |
|
| 118 |
context = torch.randn(4, 512) # 4 series, 512 past timesteps
|
| 119 |
+
out = model.predict(context, horizon=64, quantiles=[0.1, 0.5, 0.9])
|
| 120 |
out.quantiles # (4, 64, 3)
|
| 121 |
out.median # (4, 64)
|
| 122 |
```
|
| 123 |
|
| 124 |
`predict` accepts PyTorch tensors and NumPy arrays.
|
| 125 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 126 |
### Forecasting With Covariates
|
| 127 |
|
| 128 |
+
Anything known over the past goes in `context`. Alongside the target, extra variates attend to it and are forecast together. Anything known over the future, such as calendar features, planned promotions, or weather forecasts, goes in `future_covariates`, shaped `[B, F, context + horizon]`; the model conditions on it but does not forecast it.
|
| 129 |
|
| 130 |
```python
|
| 131 |
import torch
|
|
|
|
| 139 |
out = model.predict(
|
| 140 |
context,
|
| 141 |
horizon=64,
|
| 142 |
+
quantiles=[0.1, 0.5, 0.9],
|
| 143 |
future_covariates=future_covariates,
|
| 144 |
)
|
| 145 |
out.quantiles # (2, 64, 3)
|
| 146 |
out.median # (2, 64)
|
| 147 |
```
|
| 148 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 149 |
## Input Contract
|
| 150 |
|
| 151 |
- `context` may be shaped `(B, T)` for batched univariate forecasting.
|
| 152 |
+
- `context` may also be shaped `(T,)`; it is promoted to a single-row batch.
|
| 153 |
- `context` may be shaped `(B, V, T)` for multiple target variates.
|
| 154 |
- `future_covariates`, when provided, should be shaped `(B, F, context + horizon)`.
|
| 155 |
+
- NaN values are treated as missing observations.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 156 |
- `horizon` must be at least 1.
|
| 157 |
- Requested quantiles must be non-empty, sorted ascending, unique, and in `(0, 1)`.
|
| 158 |
- The model was trained to emit quantiles `0.1`, `0.25`, `0.5`, `0.75`, and `0.9`.
|
| 159 |
+
- Requested quantiles are produced by inference-time interpolation when needed.
|
|
|
|
| 160 |
- Horizons up to 1024 timesteps are decoded in one forward pass.
|
| 161 |
- Longer horizons use autoregressive rollout.
|
| 162 |
- Returned forecasts are finite `float32` tensors on the model's device.
|
|
|
|
| 165 |
|
| 166 |
`t0` is a decoder-style patch transformer.
|
| 167 |
|
| 168 |
+
It encodes each patch from values, within-patch time index, and validity mask. The transformer alternates causal time-axis self-attention with variate-axis group self-attention. Time attention uses time-aware rotary embeddings. Variate attention lets variates in the same sample attend to one another. The stack uses pre-norm RMSNorm blocks, SwiGLU feed-forward layers, and a quantile head.
|
| 169 |
+
|
| 170 |
+
At inference, target and historical variates are normalized with causal running statistics. Future covariates use per-row global statistics.
|
| 171 |
|
| 172 |
| Field | Value |
|
| 173 |
| --- | --- |
|
|
|
|
| 180 |
| Feedforward dim | 2048 |
|
| 181 |
| Attention heads | 8 |
|
| 182 |
| Patch size | 32 |
|
| 183 |
+
| Dropout | 0.1 |
|
| 184 |
| Scaler | causal mean/std with `arcsinh` transform |
|
| 185 |
| Native quantile levels | 0.1, 0.25, 0.5, 0.75, 0.9 |
|
| 186 |
|
| 187 |
## Evaluation
|
| 188 |
|
| 189 |
+
`t0-alpha` is reported on the [GIFT-Eval leaderboard](https://huggingface.co/spaces/Salesforce/GIFT-Eval).
|
| 190 |
|
| 191 |
+
| Benchmark | CRPS | MASE |
|
| 192 |
+
| --- | ---: | ---: |
|
| 193 |
+
| GIFT-Eval | 0.4941 | 0.7240 |
|
|
|
|
|
|
|
| 194 |
|
| 195 |
Users should also evaluate `t0-alpha` on their own historical backtests. Useful checks include quantile loss, CRPS, MASE, empirical quantile coverage, calibration, and breakdowns by frequency, horizon, domain, history length, and covariate availability.
|
| 196 |
|
| 197 |
## 🧰 Public API
|
| 198 |
|
| 199 |
+
- `T0Forecaster`: The actual PyTorch module class.
|
| 200 |
+
- `Forecast`: return object encapsulating forecasted quantiles.
|
| 201 |
+
- `T0Config`: dataclass to configure the model.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 202 |
|
| 203 |
## 🧬 Lineage and Attributions
|
| 204 |
|
|
|
|
| 207 |
- **Toto** by Datadog ([repo](https://github.com/DataDog/toto)) and **Chronos-2** by Amazon ([repo](https://github.com/amazon-science/chronos-forecasting)) for factorizing attention in the time and variates dimension.
|
| 208 |
- **TiRex** by NXAI ([repo](https://github.com/NX-AI/tirex)) for contiguous patch masking.
|
| 209 |
|
| 210 |
+
Code-level attributions are listed in [`NOTICE`](NOTICE), all under Apache-2.0.
|
| 211 |
|
| 212 |
+
## Environmental Impact
|
| 213 |
|
| 214 |
+
Training compute and carbon emissions are not currently reported.
|
| 215 |
+
|
| 216 |
+
## 📚 Citation
|
| 217 |
|
| 218 |
```bibtex
|
| 219 |
+
@misc{tfc-t0,
|
| 220 |
+
title = {t0: A time-series forecasting foundation model},
|
| 221 |
+
author = {The Forecasting Company},
|
| 222 |
+
year = {2026},
|
| 223 |
+
url = {https://huggingface.co/theforecastingcompany/t0-alpha},
|
|
|
|
| 224 |
}
|
| 225 |
```
|
| 226 |
|
| 227 |
## ⚖️ License
|
| 228 |
|
| 229 |
+
Apache-2.0. See [`LICENSE`](LICENSE) and [`NOTICE`](NOTICE).
|
| 230 |
|
| 231 |
## Contact
|
| 232 |
|
| 233 |
+
For issues, bug reports, or API questions, please use the GitHub issue tracker:
|
| 234 |
+
|
| 235 |
+
https://github.com/theforecastingcompany/tfc-t0/issues
|